Most people with bad credit think their problem is getting approved. The bigger problem is saying yes to the first approval: on a $5,000 loan, the gap between a first offer and a shopped one can be about $1,400.
This guide is for anyone in the U.S. with a FICO score below about 670 who needs to borrow. By the end you’ll know which bad credit loans are worth a look, what rate range is realistic, how to compare bad credit personal loans without hurting your score, and which offers to walk away from.
What is a bad credit loan?
A bad credit loan is a loan made to someone whose credit score sits in the “poor” or “fair” range, and it’s usually a personal installment loan priced higher to cover the lender’s risk. FICO, the score most U.S. lenders use, calls 579 and below poor and 580 to 669 fair, on a scale that runs from 300 to 850 (myFICO).
There’s no special product called a “bad credit loan.” It’s an ordinary personal loan with a higher price tag. That’s good news, because the normal shopping rules still work. The lender that approves you first isn’t automatically the one that costs the least.
Start by pulling your score. Plenty of banks and card issuers show your FICO score for free. Write it down, because it tells you which tier of offers you’re shopping in.
Bad credit loan options compared
Borrowers with bad credit have five realistic options, and they differ most in two ways: what they cost in total and what you lose if you fall behind.
| Option | Typical cost | Credit needed | Time to repay | Main risk |
|---|---|---|---|---|
| Unsecured personal loan | About 18% to 36% APR* | Fair; some lenders accept poor | 2 to 5 years | High rate, and an origination fee can shrink what you receive |
| Secured personal loan | Often lower than unsecured* | Poor to fair, with collateral | 2 to 5 years | You can lose the car or savings you pledged |
| Co-signed loan | Priced partly on the co-signer’s credit* | Co-signer with good credit | 2 to 5 years | Your co-signer owes the debt if you don’t pay |
| Credit union payday alternative loan (PAL) | Capped at 28% APR; application fee up to $20 | Credit union membership; rules vary | 1 to 12 months | Small amounts only, up to $2,000 |
| Payday loan | Often close to 400% APR | Usually no credit check | Typically 2 weeks | Rollovers stack fees quickly |
*Illustrative ranges. Your actual rate depends on your credit profile and the lender. PAL limits come from the NCUA; the payday figure comes from the CFPB.
For most people, the real choices are in the first three rows. The last two are for small, short-term needs. The PAL is the safe version of that; the payday loan is the expensive one.
Mark the rows you actually qualify for. If you own a car outright or know someone with good credit who’d co-sign, get quotes for those too. They can move your rate more than anything else on this page.
Compare bad credit personal loans in one place. Loans.net shows prequalified offers from multiple lenders using a soft credit check, so looking won’t affect your score.
How bad credit personal loans work
A bad credit personal loan is an installment loan: you get a lump sum up front and pay it back in fixed monthly payments, usually over two to five years.
Three numbers decide what you’ll pay. The APR is the yearly cost of the loan, including most fees. The term is how many months you’ll be paying. The origination fee is a one-time charge, often somewhere between 1% and 10% of the loan (illustrative), that many lenders take out before the money reaches you.
An unsecured loan needs no collateral. Approval rests on your income, your existing debt and your credit history. A secured loan is backed by something the lender can take if you stop paying, usually a paid-off car or a savings account. Secured typically means easier approval and a lower rate, with a real asset on the line. Our guide to secured vs. unsecured loans goes deeper.
How to get a bad credit personal loan, step by step
- Check your credit reports for errors. Get them free at AnnualCreditReport.com, the federally authorized site, and dispute anything that’s wrong. Removing one mistaken late payment can lift your score.
- Work out your debt-to-income ratio. Add up your monthly debt payments and divide by your gross monthly income. The lower that number, the better you look to a lender.
- Pick an amount and a term. Borrow only what you need, and choose the shortest term whose payment you could still cover in a tight month.
- Prequalify with several lenders. Prequalification uses a soft credit check, so you can see likely rates without any effect on your score.
- Compare offers on total cost. Add the fee and the total interest for each one. Ignore the monthly payment until you’ve done this.
- Read the agreement before you sign. Look for the fee, any prepayment penalty and any autopay discount. The formal application is when the hard inquiry happens.
Set aside 30 minutes and finish steps 1 through 3 before you fill out a single application. Those three steps decide which offers you’ll see.
What to have ready before you apply
Lenders verify who you are and what you earn, and an application can sit in limbo while they wait for a missing document. Most applications ask for:
- A government-issued photo ID
- Your Social Security number
- Proof of income: recent pay stubs, or tax returns and bank statements if you’re self-employed
- Proof of address, such as a utility bill or lease
- Bank account details for the deposit and for autopay
- Details on any collateral, like the car’s title, if you’re applying for a secured loan
Put these in one folder on your phone before you prequalify. When the offer you want comes in, you can finish the application the same day instead of letting it sit.
What rate can you get with bad credit?
With bad credit, personal loan APRs usually land somewhere between the high teens and the mid-30s, depending on your score, your income and the lender (illustrative range).
| Credit profile | Typical APR* | What it usually means |
|---|---|---|
| Poor (below 580) | 25% to 36% | Fewer lenders will approve; collateral or a co-signer helps most |
| Fair (580 to 669) | 18% to 32% | More lenders will quote; comparing offers pays off |
| Rebuilding | Varies | Prequalify with soft checks to see where you land |
*Illustrative ranges for the U.S. market, not a quote or an offer. Rates, fees and terms are set by each lender.
Many mainstream personal loan lenders stop at about 36% APR. That’s also the limit federal law puts on most consumer loans to active-duty service members and their families under the Military Lending Act (CFPB). An offer far above that line is a different and much more expensive product.
What moves the rate you’re quoted
- Your score tier. Going from poor to fair changes which lenders will quote you at all.
- Your debt-to-income ratio. Less existing debt per dollar of income means a lower rate.
- How steady your income is. Documented, regular pay can make up for a weak score.
- Collateral. Pledging a car or savings lowers the lender’s risk and usually your rate.
- A co-signer, whose credit can count toward the approval and the pricing.
- The amount and the term. A smaller loan is easier to approve, and a shorter term means less total interest.
Two of these matter far more than the rest: your score tier, and whether you can add collateral or a co-signer. Autopay discounts and small term changes help too, but they’re the small stuff.
Before you apply, work on the one factor you can change this month. For most people, that’s paying a card balance down or lining up a co-signer.
Worked example: first offer vs. a shopped offer
Taking the first bad credit loan you’re offered can cost about $1,400 more than shopping around for the same $5,000.
Say you need $5,000 in hand and you want to pay it off in 36 months.
Offer A comes in first: a 32% interest rate with an 8% origination fee. To walk away with $5,000, you have to borrow about $5,435, and the $435 fee comes out up front. The payment is about $237 a month.
Offer B takes a morning of comparing: 22% with a 3% fee. You borrow about $5,155, the fee is $155, and the payment is about $197 a month.
| Offer A (first offer) | Offer B (shopped) | |
|---|---|---|
| Amount borrowed | $5,435 | $5,155 |
| Origination fee | $435 | $155 |
| Interest rate | 32% | 22% |
| Monthly payment (36 months) | About $237 | About $197 |
| Total interest | About $3,087 | About $1,932 |
| Total repaid | About $8,522 | About $7,087 |
| Total cost of getting $5,000 | About $3,522 | About $2,087 |
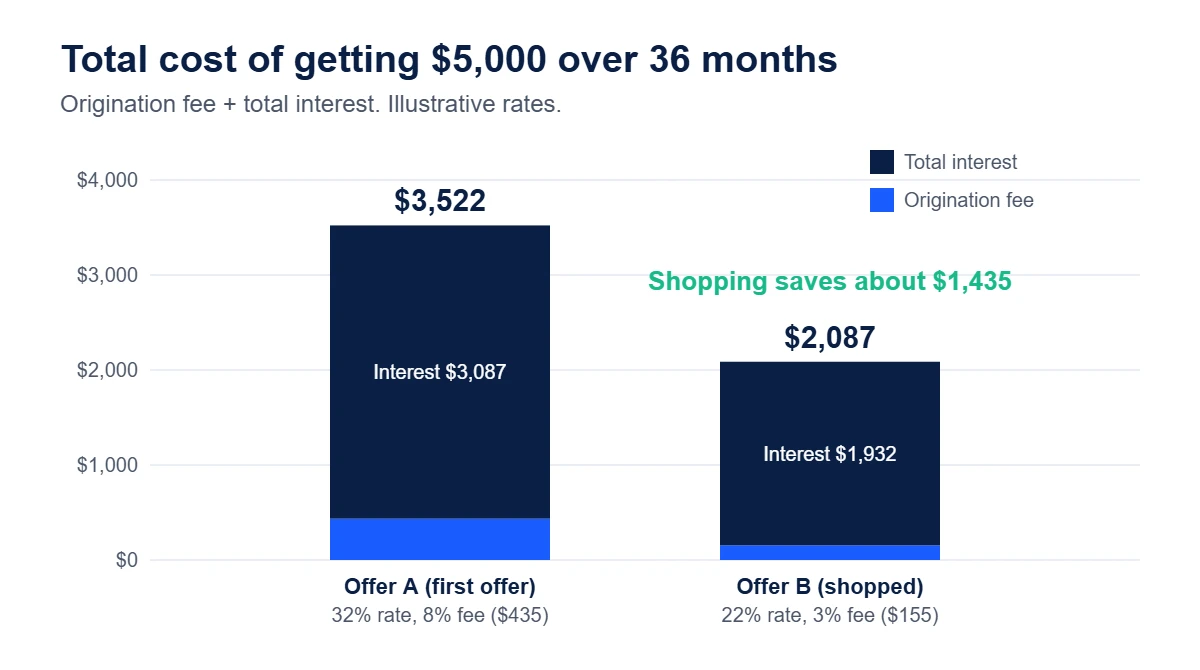
Same $5,000 in your pocket. Offer B costs about $40 less a month and about $1,435 less overall. I’d take the shopped offer every time.
Rates are illustrative. Your rate depends on your credit profile and the lender.
When your offers come in, add the fee and the total interest for each one, then sort by that number. The lowest total wins, even when its monthly payment isn’t the lowest. You can check the math with our loan calculator.
The non-loan option: a debt management plan
If you’re borrowing to pay off credit cards, a debt management plan through a nonprofit credit counseling agency may cost less than any bad credit loan.
In a debt management plan, you make one payment a month to the counseling agency, and it pays your creditors. Counselors often get card issuers to lower interest rates or waive some fees. Plans require on-time payments and can take 48 months or more to finish (FTC; CFPB).
A plan fits when high-interest cards are the problem. It doesn’t fit when you need cash for a car repair or a medical bill.
If cards are your problem, book a free first session with a nonprofit credit counselor before you apply for a loan. Our debt consolidation guide covers the loan route side by side.
Is a bad credit loan right for you?
A bad credit loan makes sense when what you’re paying for is worth more than the loan costs, and the payment still fits your budget in a bad month.
It’s usually a good fit when:
- It replaces more expensive debt, like a payday loan or cards charging a higher rate.
- It pays for something that protects your income, such as fixing the car you drive to work.
- You could still make the payment if your overtime or side income disappeared.
The answer is no when:
- You’d be using it to cover regular monthly bills. A loan only pushes that gap back, with interest added.
- The only offers you can get are above 36% APR.
- You’d need to stretch the term just to make the payment work.
Take the monthly payment from your best offer and subtract it from what’s left over in your leanest month. If the result is below zero, wait or borrow less.
Red flags: predatory loans and scams to avoid
The clearest red flag is a lender that guarantees approval before looking at your credit and then asks you to pay something up front.
According to the FTC, legitimate lenders don’t promise a loan before they’ve seen your credit history, and no legitimate lender asks you to pay a fee in advance to get one. Scammers call that fee “processing,” “insurance” or “application,” and often want it by wire transfer, gift card or cryptocurrency so you can’t get it back.
Payday loans aren’t scams, but the math is brutal. A typical two-week payday loan with a $15 fee per $100 borrowed works out to an APR of almost 400% (CFPB). Roll a $500 payday loan over every two weeks for five months and you’ve paid ten $75 fees, $750 in total, and you still owe the original $500. (Illustrative; state laws limit rollovers.)
Walk away if you see any of these:
- “Guaranteed approval” or “no credit check” on a large loan
- A fee you have to pay before you get the money
- Requests to pay by wire transfer, gift card or cryptocurrency
- Pressure to sign today
- No physical address or no state license
- No APR shown before you apply
Before you apply anywhere, look the lender up on your state financial regulator’s website to confirm it’s licensed. If anyone wants money before you get yours, stop there.
How a bad credit loan affects your credit score
A formal application usually costs your score a few points at first, and making every payment on time can raise it over the long run.
Prequalifying uses a soft inquiry, which doesn’t affect your FICO score. The formal application triggers a hard inquiry. For most people, one extra hard inquiry takes less than five points off their FICO score, and inquiries make up only about 10% of the score (myFICO).
The bigger effect comes later. Payment history makes up 35% of your FICO score, more than any other factor (myFICO). A loan you pay on time every month builds that history. A single missed payment damages it. Our guide on how to improve your credit covers the rest of the rebuild.
Set up autopay for the day after your paycheck lands. Many lenders knock a little off the rate for autopay, and it protects the biggest part of your score.
Other ways to borrow with bad credit
If a personal loan isn’t the right fit, a few alternatives either cost less or build your credit faster.
- Federal credit unions can make payday alternative loans (PALs) from $200 up to $2,000, with terms from one to 12 months, an interest rate capped at 28% and an application fee of no more than $20 (NCUA). You have to be a member of the credit union.
- A secured credit card or a credit-builder loan won’t get you cash today, but both build payment history, so your next loan costs less.
- A co-signer with good credit signs with you and shares legal responsibility for the debt.
- If you borrow from family, write down the amount, the payment and the due date, and both sign it. Clear terms keep it from turning into a fight.
- If the bill you’re trying to cover is owed to a hospital, utility or card issuer, ask that company for a payment plan before you borrow.
If you need less than $2,000, call your local credit union before any online lender and ask whether it offers PALs.
Frequently asked questions
Can I get a personal loan with a 500 credit score?
Possibly, but fewer lenders will approve you. With a score around 500, offering collateral or adding a co-signer with good credit gives you the best chance. You’ll also see the highest rates, so compare several prequalified offers before you choose one.
What interest rate will I get on a bad credit loan?
Usually somewhere from the high teens to about 36% APR (illustrative). Your score tier, income, existing debt and whether you add collateral or a co-signer decide where you land, and each lender prices differently.
How much can I borrow with bad credit?
Usually less than a borrower with good credit could get for the same income. Lenders size the loan to your income and existing debt, so a lower debt-to-income ratio, collateral or a co-signer can raise the amount you’re offered. Ask for only what you need; a smaller loan is easier to approve and cheaper to repay.
Do bad credit loans come with guaranteed approval?
No. Legitimate lenders don’t guarantee approval before they review your credit, and the FTC names “guaranteed” loans with upfront fees as a common scam. Treat any guarantee as a warning sign.
Will checking rates on Loans.net hurt my credit?
No. Comparing prequalified offers on Loans.net uses a soft credit check, which doesn’t affect your score. A hard inquiry only happens when you formally apply with the lender you pick.
How fast can I get a bad credit loan?
Often within a few business days after approval. The timing depends on the lender, how quickly you can verify your identity and income, and your bank.
Is a payday loan a good option if I have bad credit?
Usually not. A typical payday loan works out to an APR of almost 400%, according to the CFPB. If you need a small amount, ask a credit union about a payday alternative loan, which is capped at 28%.
Can a bad credit loan help rebuild my credit?
Yes, if the lender reports to the credit bureaus and you pay on time every month. Payment history is 35% of your FICO score, so steady on-time payments are one of the fastest ways to rebuild.
What’s the difference between secured and unsecured bad credit loans?
A secured loan is backed by collateral, like a car or savings; an unsecured loan isn’t. Secured loans are usually easier to get and cheaper, but you can lose the asset if you stop paying.
Related guides
- Personal loans: compare rates and lenders
- Secured vs. unsecured loans
- Debt consolidation loans
- Installment loans
- How to improve your credit
- Loan calculator
Compare bad credit personal loans now
See prequalified offers from multiple lenders in minutes, with no effect on your credit score. Sort them by total cost and pick the one that fits your budget.
Last updated: September 24, 2026. Published by Loans.net. Read our editorial policy.
Sources: myFICO: credit score ranges; myFICO: credit inquiries; CFPB: payday loan APR; CFPB: Military Lending Act; NCUA: payday alternative loans; FTC: advance-fee loans; FTC: how to get out of debt. All sources accessed September 2026.
Loans.net is a free comparison marketplace, not a lender. We don’t make credit decisions or set rates, fees or terms; participating lenders do. Rates on this page are illustrative examples, not offers. This page is general information, not financial or legal advice.